When you hear return on investment, you probably think about stocks, retirement accounts, real estate, or other traditional ways to build wealth. But what if you applied that same question to the money you spend daily?
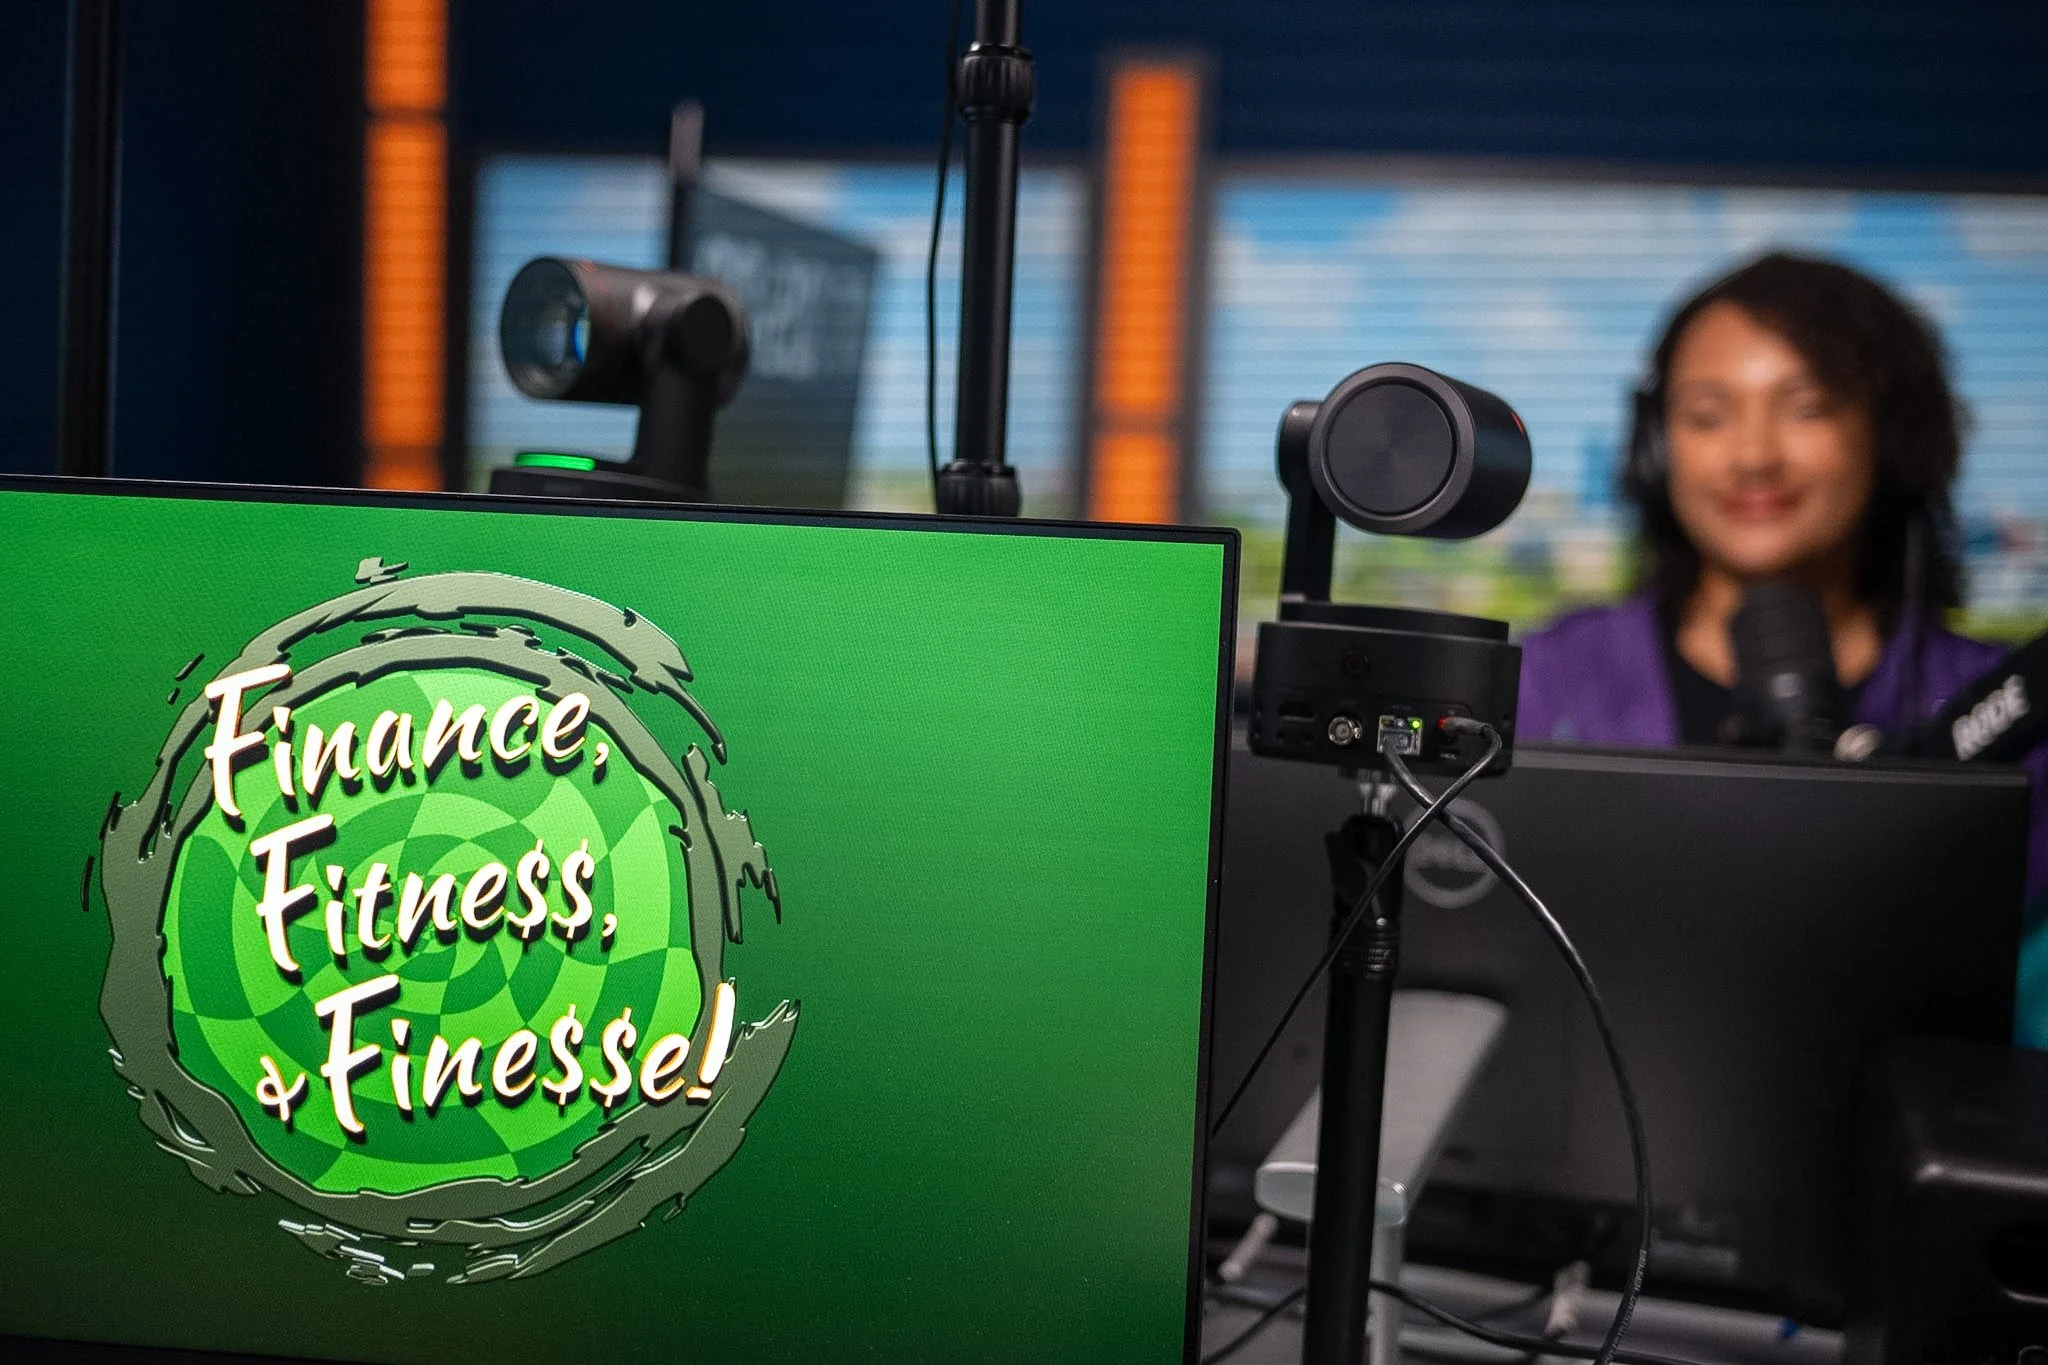
In this episode of Finance, Fitness & Finesse, JaeVic explores the connection between return on investment, impulsive spending, money psychology, advertising, household finances, childcare, work, and financial decision-making. The conversation looks beyond "just make a budget" advice and asks a more important question: Can you understand and trust your own spending decisions?
What Is the ROI of Your Spending?
Return on investment, or ROI, is usually associated with investing money with the expectation of receiving something of value in return. You can apply that same framework to everyday spending, but understanding your daily ROI is a skill that takes time to develop.
In financial therapy, we explore the return on investment from both a financial and emotional perspective. A purchase may make financial sense on paper while meeting an emotional need, such as comfort, connection, relief, or a sense of control. Learning to recognize both sides helps you better understand what drives your spending and whether the return aligns with what you actually need and value.
Understanding your ROI also means understanding your capacity. Your time, energy, emotional needs, financial resources, and current responsibilities all influence what makes a purchase worthwhile. Financial therapy can help you build the awareness to evaluate these factors, recognize your spending patterns, and make decisions that support both your financial goals and emotional well-being.
Instead of asking only:
"Should I spend this money?"
Try asking:
"What am I getting holistically in return, financially and emotionally?"
You Are Being pressured to Spend Constantly
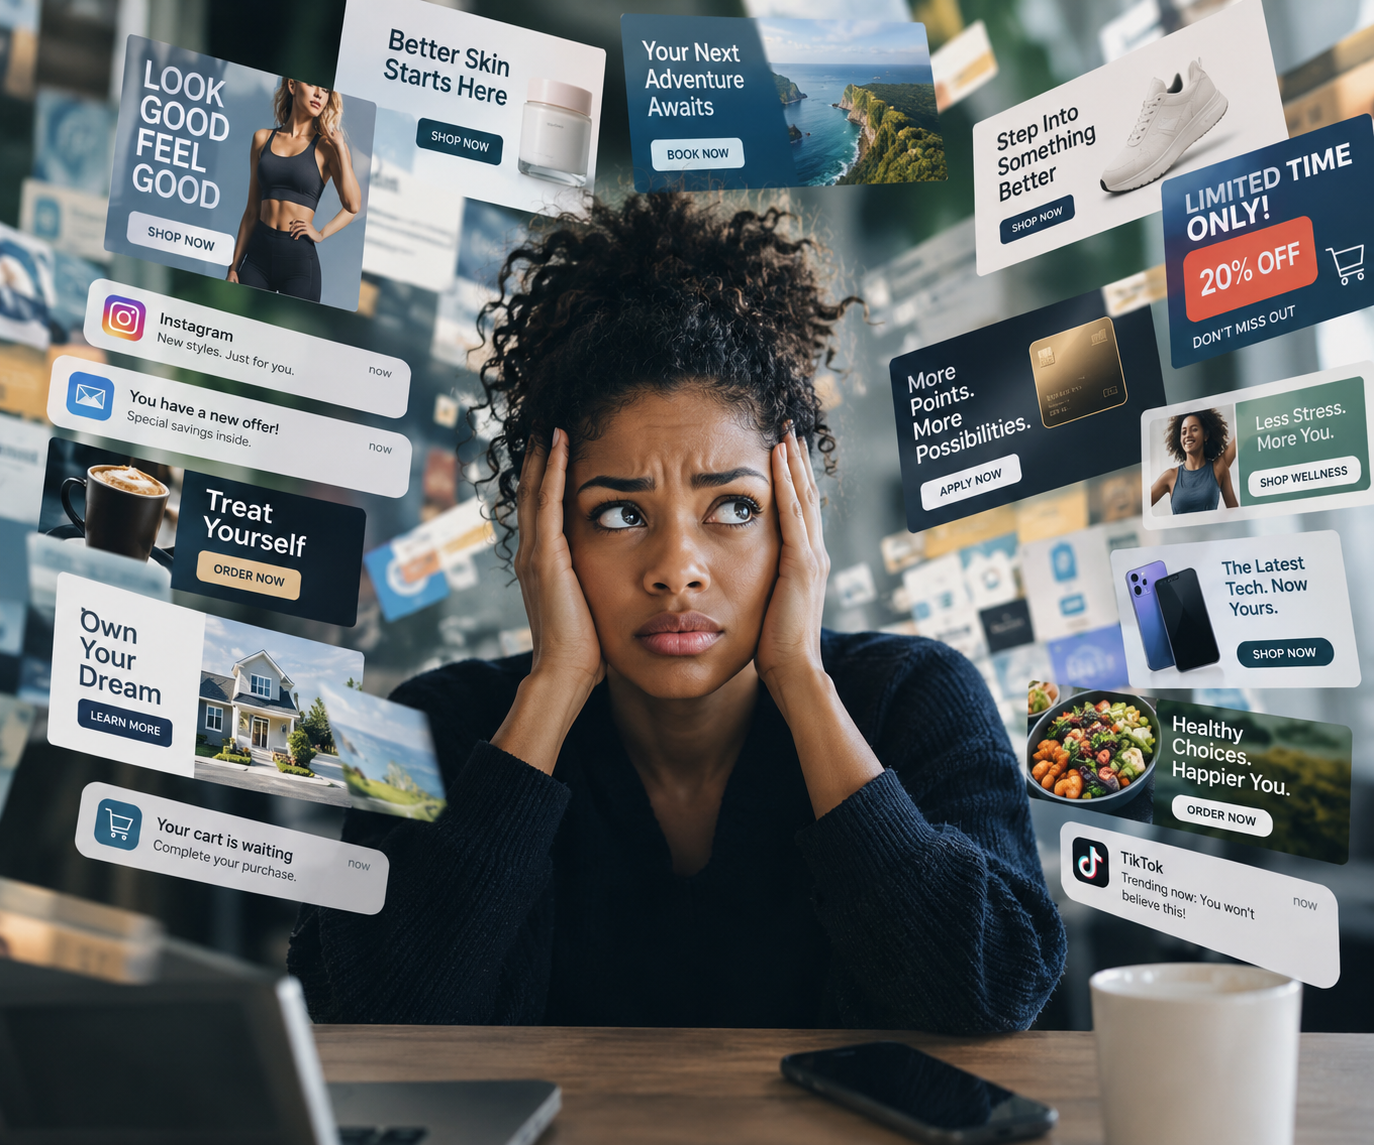
The episode also explores the role advertising plays in our spending behavior. The conversation references the idea that consumers may encounter thousands of advertisements every day, with estimates often discussed in the range of 4,000 to 10,000 ads.
Whether every person actually encounters that exact number is less important than the larger point: we live in an environment where we are constantly being encouraged to buy. Ads can create anxious urgency. They can make products feel necessary. They can connect purchases to identity, success, convenience, beauty, happiness, or belonging.
When you combine that constant exposure with an easy online checkout process, impulsive spending becomes much easier. That means your spending habits are not developing in isolation. They are being influenced by your environment.
Impulsive Spending Is Not Always About Self-Control
One of the biggest mistakes we can make when talking about money is assuming that impulsive spending simply means someone lacks discipline. Most often there is much more happening underneath the purchase. Consider a working mother who is balancing employment, childcare, household responsibilities, and the mental load that comes with managing a family.
She may spend money on convenience because she is exhausted. She may pay for childcare because she needs to work. She may order takeout because cooking another meal feels impossible after a long day. She may purchase something for herself because she has spent most of the day taking care of everyone else.
Looking at the transaction without understanding the context can make the spending appear irresponsible. Looking at the entire situation can tell a very different story. This is where understanding money psychology with financial therapy matters. The goal is not to excuse every purchase. It is to understand the circumstances, emotions, needs, and beliefs influencing the financial decision.
Learn About Money by Talking About Money
One of the simplest financial empowerment tools available is conversation. Talk about money. You do not need to wait until someone has debt, a financial emergency, or a major disagreement to start. Talk about why the household spends money. Talk about what the family is prioritizing. Talk about childcare, work, savings, and desired lifestyle convenience.
Children can learn about money by hearing adults explain financial decisions. Partners can better understand each other's spending priorities by actually discussing them. Families can identify patterns that might otherwise remain invisible. Financial literacy is not only knowing financial terms. It is also developing the ability to understand, discuss, evaluate, and make decisions about money collaboratively.
A better question to ask when spending
A healthy relationship with money does not require you to question every purchase or feel guilty about every dollar. The goal is to develop enough awareness to trust your spending decisions.
The next time you are about to make a purchase, try replacing:
“Can I afford this?”
with:
“What is the return on this spending, and does it actually matter to me?”
That return might be financial, but it could also be time, career growth, family connection, better health, or an improved quality of life. A purchase you once considered unnecessary might actually be supporting something you deeply value.
The key is recognizing the difference between spending that aligns with your priorities and spending driven by impulse or external pressure.
The point is not to spend more or justify every expense. It is to make your spending more intentional, understand what you are getting in return, and feel confident that your money is supporting the life you want to live.
Need Help Creating That Pause?
If impulsive spending is something you are actively working on, having a tool that helps you pause before you purchase can make a difference.
We are partnered with Impause, an app designed to help you slow down the impulse-to-purchase cycle and make more intentional spending decisions while tracking your money all in one place. As a Dimensional Wealth community member, you can get 50% off your first year of the annual plan with code JAEVIC.
Download the app and Get 50% off Impause with JAEVIC
Financial therapy can help you explore the emotions and experiences behind the spending patterns you discover through the app. Explore our services to learn more.
Want to Go Deeper?
Read more blogs at jaevic.com/blog, then watch the F3 episode on YouTube and WCIA 3+, or listen on all major podcast platforms.
If you made it this far, you are ready to transform your relationship with money. Learn more about financial therapy, money coaching, and financial wellness with Dimensional Wealth through a free consultation.
Have a real-life money question, experience, or moment that shaped how you think about money? Share your money story through jaevic.com or email financefitnessfinesse@gmail.com for a chance to be featured on a future episode.